Since July 2022, salary-packaging an eligible electric car through a novated lease has meant paying no fringe benefits tax on it. The government says take-up has been strongest outside the inner cities, in places like Gosford, Kellyville, Werribee and Toowoomba. In the 2026-27 Budget the government said that deal will narrow. People have read that as "the exemption ends in April 2027", but that isn't what the documents say.
The short version
| When the lease commitment is made | Car costs $75,000 or less | Car costs over $75,000 (below the LCT threshold) |
|---|---|---|
| Before 1 April 2027 | Full exemption continues for that existing arrangement | |
| 1 April 2027 to 31 March 2029 | Full exemption (100% discount) | 25% discount |
| From 1 April 2029 | 25% discount for all eligible EVs | |
Treasury and the ATO both state that existing leases won't be affected. The ATO also notes plainly that the measure is not yet law. Draft legislation went out for consultation from 10 to 28 September 2026, and as of today it hasn't been passed.
What "a 25% discount" actually means
The discount isn't 25% off your lease. It works through the statutory formula the ATO uses to value a car benefit. Normally the taxable value is 20% of the car's base value each year. The ATO says the full discount works as a 0% rate, and the 25% discount as a 15% rate.
Take an EV with an $80,000 base value, used privately all year:
| Rule | Rate | Annual taxable value |
|---|---|---|
| Today (exempt) | n/a | $0 |
| Over-$75k car, committed 1 Apr 2027 or later | 15% | $12,000 |
| A non-EV for comparison | 20% | $16,000 |
The ATO formula subtracts any employee contribution from the taxable value. That's why novated leases on cars that aren't exempt usually include after-tax contributions designed to wipe out the FBT. In our example, that would mean about $12,000 a year paid from after-tax pay instead of $0. So an over-$75,000 EV leased after March 2027 loses most of its current advantage. Its taxable value is still 25% lower than a petrol car's, but it is no longer nil.
How the $75,000 is measured
The test is the car's base value when the employer (or lessor) first holds it, not the advertised price. Under the ATO's statutory formula, base value is the cost price including GST and any luxury car tax, plus dealer delivery and any non-business accessories fitted. It excludes registration and stamp duty, and is reduced by any trade-in or cash payment.
So a car advertised a little under $75,000 can end up over the line once delivery and options like tow bars or tint are added. Ask your lease provider for the base value figure in writing before you sign. A car also has to stay under the luxury car tax threshold for fuel-efficient vehicles to qualify at all. That threshold is $91,661 for 2026-27, according to the ATO.
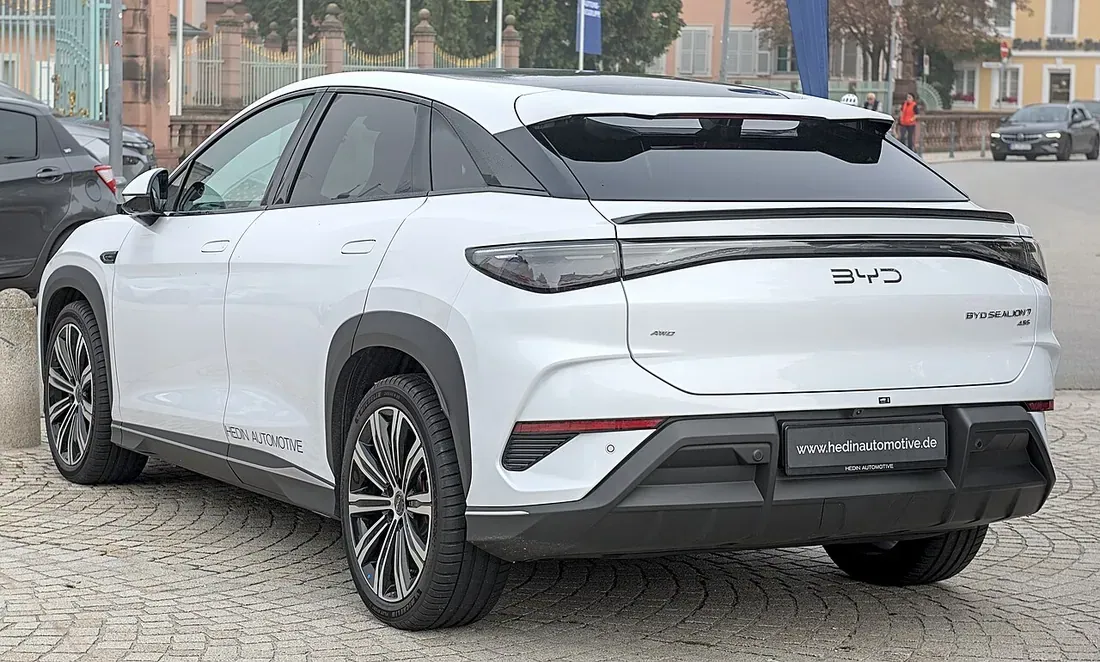
For reference, BYD's configurator lists the Sealion 7 Premium at $54,990 and the Performance at $63,990, so both sit comfortably under the line. All twelve cars in our cheapest EVs list are under $35,000.
Who should act before 1 April 2027?
Buying an EV over $75,000? This is the group with a deadline. Under the draft, a commitment made before 1 April 2027 keeps the full exemption for as long as that arrangement runs. After that date, the same car gets only the 25% discount.
Buying an EV of $75,000 or less? No rush. The full exemption continues for commitments made up to 31 March 2029.
Changing jobs with a lease in place? The protection is tied to the commitment made in your current job. In its submission, Chartered Accountants ANZ warned that the draft may not carry grandfathering across when an employee moves to another employer, even within the same corporate group. That issue is still open, so check with your provider before you move a lease.
Things that don't change
The exempt car is still a reportable fringe benefit. It appears on your income statement and counts toward income tests such as the Medicare levy surcharge, even though no FBT is paid. Plug-in hybrids have been outside the exemption since 1 April 2025, except under certain conditions for arrangements already in place. For home charging, employers can use the ATO's shortcut rate, which is 5.47 cents per kilometre for the 2026-27 FBT year.
Comparing cars before you sign? Filter by price, range and charging speed in the EV Select database, and see what fuel savings add up to in our running-cost breakdown.
Quick answers
Is the EV FBT exemption ending in 2027?
Not entirely. Under the government's proposal, EVs costing $75,000 or less keep the full exemption for commitments made before 1 April 2029. EVs over $75,000 (but under the luxury car tax threshold) drop to a 25% FBT discount for commitments made from 1 April 2027. The change is not yet law.
Will my existing novated lease be affected?
Treasury and the ATO say existing leases won't be affected. The draft protects arrangements committed to before the relevant date. Changing employer may count as a new commitment, so check before you move a lease.
What is the EV FBT threshold?
$75,000, measured as the car's base value: cost price including GST, dealer delivery and fitted non-business accessories, excluding registration and stamp duty. The car must also be under the fuel-efficient LCT threshold, which is $91,661 for 2026-27.
What does the 25% FBT discount mean in dollars?
The statutory rate drops from 20% to 15% of the car's base value. For an $80,000 EV used all year, the taxable value would be $12,000, compared with $0 today and $16,000 for a non-EV.
- Treasury Ministers, "Fairer tax treatment to encourage affordable EVs" (5 May 2026)
- ATO, "Electric car discount – more sustainable FBT treatment of electric cars" (updated 14 May 2026)
- Treasury consultation, "Sustainable fringe benefits tax treatment of electric cars" (closed 28 Sep 2026)
- ATO, Electric cars exemption
- ATO, Taxable value of a car fringe benefit (statutory formula)
- ATO, Luxury car tax rate and thresholds
- ATO, Consequences of having a reportable fringe benefits amount
- Chartered Accountants ANZ, submission media release on the EV FBT draft
- BYD Australia, Sealion 7 build & price